


COVID-19 and access to agricultural finance in Uganda
COVID-19 and access to agricultural finance in Uganda
During August and September, Wellspring Development Capital and Sofala Partners conducted a “rapid diagnostic” on the impact of COVID-19 on agricultural finance in Uganda, on behalf of Financial Sector Deepening Uganda (FSDU). We consulted more than 85 experts and practitioners across the country, from those involved in farming and agro-processing, to traders and exporters, commercial banks, NBFIs, SACCOs, regulators, development partners, and more. We would like to express our sincere thanks to those who took the time to share insights with us.
Related Posts
 Mitigating the Impact of Covid on Gains in Financial Inclusion
 The Overall Impact of COVID on The Economy; An Agile Scenario Analysis

The impact of Pandemics on Poverty and Financial Inclusion
The impact of Pandemics on Poverty and Financial Inclusion

By Rashmi Pillai, Executive Director.
By now, the novel Coronavirus disease (COVID-19) – is a household term. Hand sanitizer is out of stock, businesses are closing or cutting staff, and even boda-boda riders near the FSD Uganda office report possible plans to stop working and go back to the village because they aren’t earning enough to remit back to their families. The pandemic is another reminder of our global interconnectedness. It is a reminder of how an issue that is completely external can dramatically influence economies, both through on the ground effects like killing tourism, and through macro level effects like disrupting trade and weakening the currency.
Related Posts

Technology Enables Access. Trust Sustains Adoption.
Technology Enables Access. Trust Sustains Adoption.
By Janani Luwum
Digital platforms are helping farmers access credit, savings, payments, markets, extension services and insurance products. They promise to make financial services more accessible, reduce transaction costs and connect underserved farmers to formal finance at scale.
Yet evidence from agricultural digitisation initiatives suggests that expanding access alone does not guarantee sustained adoption.
Since late 2022, FSD Uganda has been implementing a platform strategy approach, leveraging technology and a value chain approach to build scalable, sustainable and inclusive financial solutions. Working with Ensibuuko Tech Ltd, Emata Uganda Ltd, Quest Digital Finance and clinicPesa Ltd, the strategy has focused on strengthening institutional capacity, enhancing business models, improving products and services, and building partnerships across the digital ecosystem.
Across these platforms, one insight consistently emerged. Technology made digital financial services more accessible to farmers and they continued using them only when they trusted them.
This raises an important question not only for Uganda but for digital financial services more broadly: what does it take for digital platforms to achieve sustained adoption among underserved farmers?
Trust begins with relevance
Farmers do not adopt digital tools because they are digital. They adopt them because the services respond to real needs and improve their everyday lives.
Across the different platforms, farmers engaged with digital services when they addressed immediate challenges such as accessing credit, receiving payments, managing savings, obtaining market information and improving record keeping. Cooperative and VSLA administrators also found value in digitisation because it improved operational efficiency.
This finding aligns with broader evidence on technology adoption in agriculture. Farmers adopt digital tools when they reduce costs, improve convenience, increase income opportunities or help manage risk. Successful digital platforms therefore begin with farmer problems rather than technology solutions.
But solving real problems is only the beginning. Farmers must also have confidence in the people and institutions delivering these services. Without that confidence, even useful products struggle to achieve sustained adoption.
Trust is built through people
A common misconception is that digitisation eliminates the need for human interaction. Implementation consistently suggested the opposite.
Experiences from Emata, Quest Digital Finance and Ensibuuko showed that trusted intermediaries remained central to adoption. SACCO leaders, cooperative managers, extension workers and Digital Community Entrepreneurs played a critical role in explaining products, resolving concerns and supporting farmers through the onboarding process. Community outreach, peer testimonials, radio programmes and continuous field support all helped farmers understand and confidently use digital financial services. Rather than replacing relationships, effective digitisation strengthened them by making services more efficient while preserving trusted channels of engagement.
Trust is reinforced through reliable experiences
Initial confidence alone is not enough to sustain adoption.
Farmers continue using digital services when those services consistently deliver on their promise. They need clear information about costs, repayment terms, eligibility criteria, benefits and risks. When products are poorly explained or outcomes differ from expectations, confidence quickly erodes. Likewise, farmers remember whether payments arrive on time, whether loan applications are processed efficiently and whether support is available when problems arise.
Repeated positive experiences strengthen trust. Repeated failures weaken it.
For digital platform providers, reliability is therefore not simply an operational issue. It is fundamental to building long-term confidence in digital financial services.
Trust expands opportunities for financial inclusion
As farmers continue using digital services, they generate transaction histories, payment records and other digital footprints that make them more visible to financial institutions.
These records help reduce information gaps that have traditionally limited access to agricultural finance. More importantly, they are created through continued use. Without sustained adoption, the data needed to expand financial services simply does not exist.
Trust therefore delivers benefits that extend beyond platform usage. It creates the conditions for broader and more inclusive access to formal financial services.
The next challenge is scaling trust
The experience of Uganda’s digital agriculture ecosystem demonstrates that trust is not a by-product of digitisation. It is the foundation of sustained adoption.
Trust is not built through technology alone. It is earned when digital services solve real problems, are delivered through trusted relationships and consistently keep their promises.
For governments, development partners, financial institutions and digital platform providers, this means that investments in technology should be matched by investments in trusted delivery channels, customer protection, digital literacy and reliable service delivery.
The experience also points to a broader challenge for the sector. Building trust requires continued investment in people, partnerships and customer support. As digital platforms seek to reach more underserved communities, the next phase of innovation will not be defined by technology alone, but by finding more sustainable ways to build and maintain trust at scale.
Technology may open the door to financial inclusion. Sustained adoption depends on trust. The next frontier for digital financial services is finding scalable ways to build and maintain that trust.
Building Digital Trust: Addressing Cyber and Fraud Risks in Uganda’s Financial Sector
Building Digital Trust: Addressing Cyber and Fraud Risks in Uganda’s Financial Sector
As financial services become more digital, so does the risk.
Fraud, cyber threats and weaknesses in how institutions protect customers can undermine the trust on which digital financial inclusion depends.
At the ICTAU Summit, FSD Uganda will bring evidence from Uganda’s financial sector into the conversation on what it will take to build a more secure and resilient digital financial ecosystem.
The question is no longer only how we expand digital financial services but how we ensure people can use them safely and with confidence.

When risk management creates exclusion: Rethinking digital credit for vulnerable borrowers
When risk management creates exclusion: Rethinking digital credit for vulnerable borrowers
By Andrew Kasujja
Digital credit has transformed financial inclusion across Uganda. For millions of people, access to formal credit no longer requires visiting a bank branch, completing lengthy paperwork or providing traditional collateral. A mobile phone has become the gateway to financial services that were once inaccessible to much of the population.
Yet an important paradox is beginning to emerge.
Can a system designed to promote financial inclusion unintentionally create a new form of financial exclusion?
Digital lenders have legitimate reasons to manage credit risk. Automated lending decisions rely on repayment behaviour to determine future borrowing limits, pricing and eligibility. Borrowers who repay on time are rewarded with larger loan limits and improved access to credit. Those who default may face reduced borrowing limits, higher charges or negative credit reporting. These mechanisms are fundamental to maintaining portfolio quality and protecting lenders from excessive losses.
When temporary shocks become financial exclusion
The difficulty arises when digital systems cannot distinguish between borrowers who will not repay and borrowers who simply could not earn income temporarily.
Consider a trader whose sales collapse after several days of heavy rain, or a boda boda rider whose income falls because of temporary transport restrictions. Their repayment behaviour reflects a short-term liquidity shock rather than permanent financial distress. Yet algorithmic credit models often treat both situations identically.
The consequences can be severe.
Reduced borrowing limits, negative credit records and restricted future access to credit may leave otherwise responsible borrowers unable to finance inventory, purchase agricultural inputs or continue operating their businesses. What begins as a temporary income interruption can evolve into prolonged financial exclusion.
Ironically, the very tools designed to manage lending risk may increase economic vulnerability.
What other markets are doing differently
This challenge is not unique to Uganda. In Kenya, several digital lenders have progressively moved beyond purely repayment-based credit scoring by incorporating broader mobile money transaction histories, merchant payments and customer behaviour into lending decisions. These richer datasets provide a more comprehensive understanding of borrowers’ financial capacity than missed repayments alone.
In India, digital lending innovation increasingly leverages the country’s digital public infrastructure, including identity, payments and consent-based data-sharing, to assess borrowers using multiple data sources rather than relying exclusively on historical defaults. The emerging account aggregator framework enables borrowers to securely share financial information from different institutions, allowing lenders to make more informed lending decisions and reducing unnecessary exclusion for customers with limited traditional credit histories.
These examples demonstrate an important principle: better information produces better risk management.
What could change in Uganda?
Uganda can adopt similar approaches while tailoring them to local realities.
First, lenders should increasingly incorporate real-time cash-flow information rather than relying predominantly on repayment history. Mobile money transactions, merchant payment activity, utility payments and digital savings patterns can provide valuable insight into whether repayment difficulties reflect temporary disruption or long-term financial deterioration.
Second, digital credit products should better match borrower income cycles. Farmers should not be expected to repay according to the same schedule as salaried workers. Traders with seasonal income require different repayment structures from daily transport operators.
Third, digital savings and emergency liquidity products should accompany digital lending. Borrowers with small precautionary savings are significantly better positioned to absorb temporary income disruptions without falling into default.
Fourth, lenders should adopt graduated recovery mechanisms before imposing severe penalties. Short repayment extensions, restructuring options or temporary repayment holidays following verifiable external shocks can preserve both customer relationships and portfolio quality.
Fifth, regulators may wish to review whether existing digital credit reporting frameworks adequately differentiate temporary liquidity events from persistent default. Credit information systems should support responsible lending while avoiding unnecessary exclusion of otherwise creditworthy borrowers.
From access to resilient inclusion
The broader lesson is that digital finance should not simply automate traditional lending processes. It should improve them.
Technology enables lenders to collect more data, analyse borrower behaviour more intelligently and develop products that reflect how people earn incomes. Used effectively, artificial intelligence and alternative data can strengthen both financial inclusion and risk management simultaneously.
Uganda has made remarkable progress in expanding digital access to finance. The next frontier is ensuring that digital credit systems are sufficiently sophisticated to distinguish temporary hardship from genuine credit risk.
Financial inclusion should not end with the first missed repayment. The real measure of success is whether borrowers who experience temporary setbacks can recover, rebuild and continue participating in the formal financial system. That is the transition Uganda’s digital credit ecosystem must now make, from expanding access to building resilient inclusion.
FSD Uganda Appoints Zerubabel Kwebiiha Junior as Chief Executive Officer
FSD Uganda Appoints Zerubabel Kwebiiha Junior as Chief Executive Officer
The Board of Directors of Financial Sector Deepening Uganda (FSD Uganda) is pleased to announce the appointment of Mr. Zerubabel Kwebiiha Junior as Chief Executive Officer, effective August 3, 2026.
Zerubabel Junior is a visionary leader and institution builder with over 17 years of experience at the intersection of financial inclusion, digital innovation and private sector development across Africa. He has built and led organisations from the ground up, driven policy change at a national level and delivered commercial results at scale across some of the continent’s most complex markets.
He is the Co-founder of Reclaim Investments, a circular economy enterprise he built from scratch that is transforming livelihoods for waste pickers in Uganda, a reflection of his passion for building businesses that create lasting impact. As Global Head of Commercial at ENGIE Energy Access, he led commercial strategy across nine African countries, and as Country Director in Mozambique, he led the company to become the country’s leading solar home systems provider. At the United Nations Capital Development Fund (UNCDF) in Zambia, he was part of the team that helped increase formal financial inclusion from 4% to over 43% of the adult population—one of Africa’s most significant advances in financial inclusion. Earlier in his career, he served as Chief Executive Officer of EzeeMoney and was part of the team that rolled out and scaled MTN Mobile Money in Uganda.
Most recently, Zerubabel Junior worked with FSD Uganda supporting the Digital Economy pillar, giving him a deep understanding of the organisation, its programmes and the ecosystem it serves. He also brings governance experience through his role as a Non-Executive Director at Ecobank Uganda and other institutions.
As FSD Uganda continues to strengthen inclusive financial markets, generate evidence, influence policy and catalyse market development, Zerubabel Junior’s experience in building institutions, forging partnerships and driving innovation will help advance the organisation’s mission and long-term sustainability.
He believes that financial markets, when designed well, can be one of the most powerful forces for human dignity and economic transformation. That conviction, combined with his track record of building institutions that last, makes him the right leader for FSD Uganda at this defining moment.
We are delighted to welcome Zerubabel Junior to FSD Uganda and look forward to what we will accomplish together.

MSE Recovery Fund Annual Report 2025
MSE Recovery Fund Annual Report 2025
The 2025 MSE Recovery Fund Annual Report looks at what four years of working through Uganda’s grassroots financial institutions are teaching us about expanding finance to micro and small enterprises.
Between 2022 and 2025, participating financial institutions provided 334,318 loans to 146,009 MSEs, with UGX 381.24 billion reaching enterprises. More than 70% of borrowers were women-owned enterprises, while youth-led businesses accounted for about 44%.
But scale is only part of the story. The experience points to a more important lesson: credit can help businesses stay afloat, but finance alone is not enough to unlock sustained growth and employment. Business development support, stronger data and digital systems, more appropriate products, and deliberate approaches to reaching underserved groups all matter.
The report examines these lessons, the gaps that remain, and what they mean for building a more inclusive and resilient financial ecosystem for Uganda’s MSEs.

Bridging the Financing Gap for Women in Informal Cross-Border Trade
Bridging the Financing Gap for Women in Informal Cross-Border Trade
Women informal cross-border traders play a critical role in regional trade, food security, and household livelihoods, yet they remain among the most financially underserved entrepreneurs. This technical brief explores the experiences of women trading through the Goli border and examines the barriers that continue to limit their access to appropriate financial services. Drawing on insights from the Goli Cross Border Women Multi-Purpose Cooperative, the brief identifies practical opportunities for financial service providers, policymakers, and development partners to design solutions that better meet the needs of this often-overlooked segment.

2025 Annual Report
2025 Annual Report
Financial inclusion in Uganda has come a long way. Access to financial services has expanded, digital payments have become part of everyday life, and new technologies are reshaping how people save, borrow, invest, and transact.
Yet access alone is no longer the central challenge.
The next frontier is ensuring that financial services are used in ways that improve resilience, support livelihoods, and create meaningful economic opportunity for those who remain underserved.
FSD Uganda’s 2025 Annual Report reflects on this transition. It captures key lessons from our work across digital financial services, the digital economy, access to long-term finance, gender equity, and research. It also marks the conclusion of our previous strategic period and the beginning of a new phase focused on deeper inclusion, stronger market systems, and greater impact at scale.
Beyond reporting on activities, the report highlights emerging insights on what it takes to build financial systems that work for women, youth, smallholder farmers, and micro, small and medium enterprises.
We invite you to explore the findings, lessons, and opportunities shaping the future of financial inclusion in Uganda.

Financial inclusion starts with visibility: What Uganda’s MSE Recovery Fund reveals about kYC and data
Financial inclusion starts with visibility: What Uganda’s MSE Recovery Fund reveals about kYC and data
By the MicroSave Consulting Team
Financial inclusion starts with visibility. Before entrepreneurs can access credit, insurance, savings, or business support, they must first be recognised by the systems designed to serve them. Yet across much of Sub-Saharan Africa, millions of Micro and Small Enterprises (MSEs) remain invisible to formal financial institutions not because they lack viable businesses, but because the systems used to identify and assess them fail to capture their realities.
Know Your Customer (KYC) processes sit at the centre of this challenge. While designed to verify identity and manage risk, KYC systems also determine what financial institutions know about their customers and what they do not. When these systems are rigid, manual, or designed primarily for compliance, exclusion becomes embedded in the financial system itself.
Weak customer data systems contribute to exclusion in three ways:
- Invisibility: Entrepreneurs who do not fit standard categories remain unrecognised.
- Inefficiency: Manual processes slow approvals, increase costs, and introduce errors.
- Poor targeting: Without meaningful and disaggregated customer data, institutions struggle to design products that respond to different needs and circumstances.
The result is fewer customers served, weaker trust, and missed opportunities for both financial institutions and the entrepreneurs they seek to support.
The cost of invisibility
The human impact of weak customer data systems is visible in the lives of entrepreneurs across Uganda. In Seguku, John, a 38-year-old entrepreneur who has sustained 18 jobs for nearly two decades, risked being reduced to a single label because of his disability status, despite running a thriving business. In Nakivale Refugee Settlement, a young mother operating a tailoring business could easily have been excluded from financial services if her refugee documentation had been treated as invalid. In rural Kiwanga, Namirembe’s piggery and poultry enterprise was assessed using repayment assumptions better suited to retail businesses than seasonal agricultural enterprises.
These examples reveal a broader challenge. Financial exclusion is not always driven by a lack of capital or deliberate policy choices. Often, it begins with the information institutions collect, the categories they use, and the assumptions built into their systems.
The MSE Recovery Fund, implemented by a consortium led by FSD Uganda in partnership with the Mastercard Foundation, conducts regular Data Quality Assessments to verify the accuracy, completeness, and reliability of information reported by participating financial institutions. The assessments examine how institutions capture, manage, and report key indicators, particularly those relating to women, youth, refugees, and persons with disabilities.
The Fund’s 2025 Data Quality Assessment highlighted both progress and persistent challenges:
- Only 5 percent of participating financial institutions are fully digitised end-to-end, while 24 percent are partially digitised and 71 percent continue to rely largely on manual processes.
- The first Recovery Fund-supported financial institution to formally lend to refugees has opened the door for wider adoption, with another SACCO in the final stages of licensing with the Office of the Prime Minister.
- Persons with disabilities remain significantly underrepresented, accounting for just 0.77 percent of borrowers against a three percent target. While some institutions have piloted disability facilitators, many still do not systematically capture or apply disability data in lending decisions.
- Agricultural borrowers continue to face repayment structures that do not adequately reflect seasonal production cycles and income patterns.
The findings suggest that Uganda’s financial sector is moving in the right direction. However, progress remains fragile where customer information is incomplete, disconnected, or underutilised.
Why data architecture matters
Financial inclusion is often discussed in terms of products, capital, or distribution channels. Yet one of the most overlooked drivers of inclusion is data architecture the systems, processes, and information flows that determine how customers are identified, understood, and served.
One of the less visible but more significant contributions of the MSE Recovery Fund has been its influence on customer data systems.
Beyond providing capital, the Fund required participating financial institutions to strengthen their customer onboarding and reporting processes. Loan application forms were revised to capture information on disability status, refugee identity, gender, employee numbers, and sector-specific business characteristics. Institutions were encouraged to digitise onboarding processes, improving data quality and reducing administrative bottlenecks.
This seemingly simple change had important implications. It enabled participating financial institutions to make previously overlooked customer segments visible within their systems. Visibility, in turn, created opportunities for more informed lending decisions, improved reporting, and stronger accountability for inclusion outcomes.
The lesson is clear: the data institutions choose to collect shapes who becomes visible in the financial system, which risks can be assessed, and which opportunities can be financed.
Visibility creates opportunity
When customer data reflects reality, financial institutions are better positioned to serve diverse entrepreneurs.
For entrepreneurs like John, being assessed on the strength of a business rather than a label can unlock access to larger and more appropriate financing. For refugee entrepreneurs, recognition of refugee documentation as legitimate identification can open pathways to savings, credit, and business growth. For agricultural borrowers such as Namirembe, a better understanding of seasonal cash flows can support loan products that align with production cycles rather than undermine them.
Inclusive customer data systems also create broader benefits. They enable institutions to identify underserved groups, design more responsive products, strengthen risk management, and build trust with customers. Digital and interoperable KYC systems can reduce duplication, improve efficiency, and support stronger links with national identification systems, credit bureaus, and other trusted data sources. Importantly, stronger customer data does not simply improve reporting. It improves decision-making.
Building the Foundations for Inclusive Finance
For Uganda’s financial ecosystem to fully realise the benefits of inclusive customer data systems, four priorities stand out:
- Invest in interoperable digital systems: Financial institutions need platforms that can connect with national identification systems, credit bureaus, and other trusted data sources to support efficient and secure onboarding.
- Strengthen staff capacity: Frontline staff need the skills and awareness required to understand and respond to the realities of women, youth, refugees, persons with disabilities, and other underserved groups.
- Create incentives for inclusive innovation: Regulators and development partners can accelerate adoption by linking support mechanisms, guarantees, and innovation programmes to practices that strengthen inclusion.
- Use data to inform decisions: Customer information must move beyond compliance and reporting to influence product design, credit assessment, and risk management.
Inclusion starts with visibility
The future of financial inclusion will depend not only on how much capital reaches underserved entrepreneurs, but also on whether financial systems are designed to recognise them in the first place.
KYC remains an important part of that journey, but the broader lesson is about visibility. The information financial institutions collect determines who becomes visible, how risk is assessed, and ultimately who gains access to opportunity.
For Uganda’s financial sector, investing in inclusive and digital customer data systems is not simply an operational upgrade. It is foundational to building a more inclusive, resilient, and responsive financial ecosystem.

Deepening Financial Inclusion for Young Women in Uganda: Insights across Key Segments
Deepening Financial Inclusion for Young Women in Uganda: Insights across Key Segments
This paper summarises Financial Sector Deepening Uganda’s research on how young Ugandan women are accessing and using financial services. It was produced under the Young Ugandan Women’s Financial Inclusion (YUWFI) initiative, which aims to understand how young women engage with financial services at different stages of life, and how these patterns can inform more effective strategies to deepen financial inclusion and economic participation

Beyond Recovery: What Uganda’s MSEs Need to Scale
Beyond Recovery: What Uganda’s MSEs Need to Scale
Drawing on insights from over 100,000 enterprises supported through the MSE Recovery Fund, this brief explores what the evidence means for policymakers, participating financial institutions (PFIs), and development partners shaping Uganda’s MSME finance landscape

Deal Flow Facility Demand-Side(Investee) Outlook Report
Deal Flow Facility Demand-Side(Investee) Outlook Report
The Deal Flow Facility (DFF) is a non-investing technical assistance and matchmaking platform hosted by FSD Uganda and anchored within the Capital Markets Authority (CMA), with funding from the European Union.
It was established to address a structural gap in Uganda’s financial ecosystem: enterprises that have outgrown microfinance and bank lending but are not yet sufficiently prepared to access institutional capital such as private equity, venture capital, or impact investment.
This evaluation assesses the Deal Flow Facility (DFF) program performance: efficiency and effectiveness. It examines DFF’s performance and impact from inception to Q1 2025. It draws on four principal evidence sources: a structured survey of 77 enterprises at different stages of the DFF pipeline; 25 in-depth interviews with enterprise owners and managers; key informant interviews with investors, intermediaries, DFF staff, and ecosystem stakeholders; and DFF’s internal Advisory Committee reporting spanning March 2024 to Q1 2025.

Connected But Not Included: Is Owning a Mobile Phone Enough to Enter the Digital Economy?
Connected But Not Included: Is Owning a Mobile Phone Enough to Enter the Digital Economy?
By Andrew Tugume
In Arua town, a young produce trader scrolls through her smartphone between customers. She uses WhatsApp to coordinate deliveries from farmers and receives mobile money payments from Kampala buyers. Increasingly, she is also part of a growing wave of informal digital entrepreneurs using TikTok and other social media platforms to market their products. Through short videos sometimes even dancing while showcasing fresh produce she attracts customers, builds visibility, and differentiates herself in a competitive market.
This shift signals a deeper transition: mobile phones are no longer just tools for communication and transactions, but powerful platforms for marketing, creativity, and income generation in Uganda’s evolving digital economy.
She owns a smartphone. She has a mobile money wallet. She even makes digital payments. But she has never saved formally. She has never accessed digital credit. She has no insurance. She has no digital financial history that can unlock larger opportunities.
She is connected but not fully included.
Across Uganda, this is the definingparadox of digital transformation: mobile phone ownership is rising, yet meaningful participation in the digital economy remains uneven.
The Promise of Mobile Ownership
According to the Global Findex 2025 report, Connectivity and Financial Inclusion in the Digital Economy, 86 percent of adults globally now own a mobile phone. This marks a significant milestone in the expansion of digital access worldwide. In Uganda, the trajectory is similarly encouraging. 79 percent of adults own a mobile phone, and 73 percent have a financial account. At face value, these figures suggest that digital and financial inclusion are steadily advancing.
Mobile phones have become the primary gateway to the digital economy. They enable mobile money transactions, government transfers, merchant payments, cross-border remittances, online commerce, savings, and access to information opening up markets and opportunities that were once physically out of reach.
For millions, the first formal financial account was not opened in a banking hall but activated through a SIM card. Mobile phones have lowered the entry barriers to the formal financial system, expanding access beyond traditional brick-and-mortar institutions. But ownership alone does not guarantee transformation.
The Hidden Gaps Behind High Ownership
Despite high levels of mobile phone penetration, 1.3 billion adults globally remain unbanked. Many of them already own mobile phones, possess national identification, and have registered SIM cards. The issue, therefore, is not connectivity but conversion; turning access into meaningful financial participation.
Owning a phone does not automatically translate into access to affordable digital credit, secure formal savings, a verifiable financial history, consumer protection, or the ability to scale a business. Access to a device is only the first step; the surrounding ecosystem determines whether it becomes opportunity.
In many rural and peri-urban areas of Uganda, mobile phones are primarily used for receiving money, withdrawing cash, and purchasing airtime. While these functions are important, they represent only the surface layer of digital finance. The deeper layers such as savings, insurance, merchant services, credit scoring, and e-commerce integration remain significantly underutilised.

The Cost of Ownership: More Than Just a Handset
Mobile phone ownership involves more than the initial purchase of a device. It carries ongoing costs, including handset replacement, SIM registration, data bundles, transaction fees, and even charging expenses particularly in off-grid or rural communities. These recurring costs shape how individuals use their phones over time.
For low-income households, such expenses determine whether a phone remains merely a communication tool or evolves into a genuine economic platform. A feature phone may enable basic mobile money transactions, but a smartphone unlocks access to digital marketplaces, lending applications, e-commerce platforms, and a broader range of online services.
The quality of ownership matters as much as ownership itself. When affordability constraints limit consistent access to data and digital services, participation in the wider digital economy remains shallow, reinforcing the very gaps that connectivity was meant to close.
From Connectivity to Capability
The transition is not from phone ownership to financial inclusion;but a progression:
| 1 | 2 | 3 | 4 | 5 |
| Phone Ownership | Usage | Trust | Financial Capability | Economic Empowerment |
Connectivity alone does not produce inclusion; meaningful participation requires sustained engagement, trust, and the ability to use digital tools productively.
Many Ugandans today have mobile wallets but engage in limited digital activity. They receive funds, withdraw cash, and exit the digital system almost immediately. While this reflects access, it does not reflect depth of use. Such usage patterns limit the creation of transaction histories, digital credit profiles, formal savings records, and insurance coverage elements that are essential for building long-term financial resilience.
Without supportive infrastructure such as interoperable payment systems, consumer protection and affordable credit, mobile phones risk becoming endpoints rather than gateways. The challenge, therefore, is not just expanding connectivity, but converting it into sustained capability and economic empowerment.
The Digital Economy Beyond Payments
The digital economy extends far beyond mobile money transactions. While digital payments are often the first point of entry, they represent only one layer of a broader ecosystem. The digital economy includes digital agriculture platforms, e-commerce marketplaces, gig and remote work opportunities, merchant QR systems, cross-border trade facilitation, and pay-as-you-go energy solutions. These platforms create avenues for income, productivity gains, and market access previously out of reach for many households and small businesses.
For a mobile phone to become a true entry point into this ecosystem, it must connect users not only to payments but to opportunity. That transition requires more than access: it depends on digital literacy, product design tailored to low-income users, interoperability across platforms, and regulatory environments that foster trust and protect consumers. Without these enabling conditions, connectivity may expand, but meaningful participation in the digital economy will remain limited.
Turning Phones into Pathways
If mobile ownership is the doorway to the digital economy, the critical question is what turns that doorway into a meaningful pathway. Access alone is insufficient. Converting connectivity into opportunity requires affordable smartphones,reliable data , strong consumer protection and sustained digital literacy . It also depends on interoperable payment systems, tailored digital financial products designed for informal workers and SMEs, and gender-sensitive approaches that address disparities in phone access and control.
The next frontier of financial inclusion is not distributing more SIM cards. It is the deepening of usage and the deliberate building of digital capability ensuring that phone ownership translates into resilience, productivity, and long-term economic empowerment.
Conclusion: Connected Is Not Enough
Uganda has made significant strides in expanding digital access. Mobile phones have democratised access to financial services, lowered geographic barriers, and brought millions closer to the formal financial system.
Yet ownership is only the beginning. True participation in the digital economy depends on systems that convert connectivity into capability and capability into economic empowerment. Without the right infrastructure, products, protections, and skills, access risks remaining superficial.
The question is no longer whether mobile phones can enable inclusionbut whether our financial, regulatory, and innovation ecosystems are strong enough to ensure that every phone owner can fully participate.
Being connected is powerful, but being included is transformative.
How Uganda’s Micro And Small Enterprises Are Recovering And Growing Post-Covid-19
How Uganda’s Micro And Small Enterprises Are Recovering And Growing Post-Covid-19
At the height of the COVID-19 pandemic, 67 percent of Uganda’s micro and small enterprises were forced into complete closure. A year later, after the start of the pandemic, revenues and profits were still down by 19 percent and 36 percent, respectively.
To address this challenge, the Micro and Small Enterprise Recovery Fund, was launched by FSD Uganda in partnership with the Mastercard Foundation. Implemented by a consortium, the Fund designed to keep Uganda’s most vulnerable businesses afloat targeted women, youth, refugees, and persons with disabilities (PWDs). The Recovery Fund provided accessible credit, flexible repayment terms, and tailored financial services to help businesses survive and adapt.
Fast-forward to 2025, and the results are remarkable: 98 percent of MSEs supported under the Recovery Fund remain operational. The Recovery Fund has reached more than 107,000 enterprises, 71 percent of which are women-led and 45 percent youth-led, proving that inclusive finance can drive recovery and growth.

From participation to inclusion: building financial systems that work for women and youth
From participation to inclusion: building financial systems that work for women and youth
Expanding access to finance for women and youth requires more than credit. It requires financial systems designed around how people actually live, earn, save, and manage risk.
In 2025, FSD Uganda’s gender equity work focused on understanding and addressing the structural barriers that continue to exclude women, youth, and other underserved groups from meaningful financial participation. Across programmes such as Stimulating Agribusiness for Youth Employment (SAYE) project and the Micro and Small Enterprise Recovery Fund (MSERF), the emphasis shifted from access alone to improving how financial systems respond to real market needs.
Understanding barriers in youth and women’s financial inclusion
Under the SAYE project, FSD Uganda commissioned a legal, policy, and regulatory diagnostic to assess whether Uganda’s financial inclusion framework adequately responds to the needs of young people, women, and persons with disabilities in agribusiness and MSMEs.
The findings were clear. Uganda’s financial inclusion policies are largely well designed and supportive, including the National Financial Inclusion Strategy, Financial Literacy Strategy, and National Payments Policy. The challenge lies less in policy design and more in implementation.
For women and youth in Busoga, exclusion is driven more by practical constraints than legal barriers: lack of collateral, high interest rates and transaction costs, rigid loan features, weak financial literacy, limited digital infrastructure, and low awareness of available opportunities. For young people below 18, delayed access to national IDs also limits account ownership and formal financial participation.
The study also highlighted that while women and youth are often specifically targeted in financial inclusion programmes, persons with disabilities are frequently included only by default rather than through intentional design.
These findings reinforce an important lesson: improving financial inclusion requires stronger execution, better product design, and more responsive delivery systems not simply more policies.
Strengthening institutions and market readiness
FSD Uganda also supported SACCOs and financial institutions to better respond to these realities.
A gender norms diagnostic across SACCOs in Busoga showed how social norms continue to shape women’s access to and use of financial services. Women often face limited decision-making power, lower asset ownership, and reduced visibility within financial institutions themselves.
This informed targeted capacity building for SACCO leadership and staff to strengthen women’s leadership, improve inclusive product design, and promote fairer service delivery models. The goal was not only better internal practices, but stronger institutions capable of serving women more effectively.
At ecosystem level, partnerships with banks, agri-hubs, and youth platforms also helped improve financial readiness and strengthen the link between informal groups and formal financial institutions, an important step in moving from financial access to sustained usage.
Moving from isolated interventions to system change
Under the Mastercard Foundation’s Young Africa Works strategy, FSD Uganda continued to steward the Community of Practice (CoP) on Inclusive Finance as a coordination platform for inclusive finance.
The CoP responds to a common challenge across youth employment programmes: many young people especially young women, refugees, persons with disabilities, and early-stage entrepreneurs receive enterprise support but remain excluded from financial systems that are not designed for their realities.
Financial products often require formal collateral, long operating histories, and repayment structures that do not reflect informal businesses or startups. Financial literacy efforts are often fragmented and fail to drive lasting behavioural change.
The CoP brought together programme partners, financial institutions, and ecosystem actors to address these gaps collectively. Key areas included alternative credit scoring, digitisation of VSLAs, mobile-based financial literacy, startup financing models, and stronger access-to-finance measurement.
This work is helping shift the system from isolated interventions to a more deliberate financial inclusion architecture where programme design, financial products, and measurement work together.
Lessons from affirmative action in inclusive finance
In 2025, FSD Uganda also introduced an Affirmative Action approach under MSERF to address persistent regional inequities in access to finance.
The intervention recognised that standard due diligence requirements were unintentionally excluding Tier IV institutions in Northern and Eastern Uganda areas where financial exclusion is often highest.
Rather than treating this as a liquidity problem, FSD Uganda tested whether targeted institutional strengthening could prepare these institutions to sustainably absorb and manage capital.
The results were instructive. Capacity-building support improved reporting, governance awareness, and portfolio management. Some institutions recorded measurable progress, including improved portfolio recovery and stronger female membership growth.
However, the process also revealed a deeper reality: financial exclusion at this level is often an institutional problem before it becomes a financing problem. Weak governance, fragile loan books, and poor reporting systems cannot be solved through short-term capital injections alone.
The lesson was clear. Inclusion requires time, institutional readiness, and stronger foundations. Without that, liquidity alone creates risk rather than opportunity.
Looking ahead
These experiences continue to reinforce the same principle: financial inclusion for women and youth cannot be achieved through standalone interventions.
It requires systems that recognise lived realities, institutions that can serve excluded groups well, and financing models designed around trust, flexibility, and resilience.
FSD Uganda’s focus remains clear: not only expanding access to finance, but ensuring financial systems create meaningful and lasting economic opportunity for those historically left out.
Unlocking patient capital for inclusive growth
Unlocking patient capital for inclusive growth
Access to long-term finance remains one of the biggest constraints to enterprise growth in Uganda. While businesses can access short-term working capital, access to long term patient capital needed to expand operations, invest in productivity, create jobs, and scale sustainably remains a challenge.
This gap is particularly significant for small and growing businesses operating in sectors that are critical to financial inclusion, such as agribusiness, light manufacturing, education, healthcare, and financial services. These businesses serve last-mile customers, strengthen local value chains, and create livelihoods, yet many remain excluded from formal investment markets due to weak investment readiness, limited investor confidence, and fragmented market infrastructure.
FSD Uganda’s Deal Flow Facility (DFF) responds to this challenge by strengthening both sides of the market: supporting businesses to become investment ready while improving how investors engage with Uganda’s private capital ecosystem. DFF’s mandate is to support the market to build a pipe line of investible businesses and attracting the right capital to drive inclusive economic growth.
Moving businesses closer to investment
In 2025, beyond pipeline development, the DFF focused on providing support to deals to move them further down the transaction cycle to deal closure.
Investor-led engagements during the year resulted in stronger deal progression, with four new deals signed and disbursed and several others advancing into final negotiation and documentation stages.
This progress included the review of eight term sheets comprising four debt deals, three equity deals, and one convertible note. Investor feedback also generated technical assistance needs across financial management, strategic planning, and operational strengthening, while three businesses received legal transaction advisory support to help complete deal closure.
Building a stronger investment pipeline
The sectoral distribution of investor-ready businesses reflects where opportunity and impact intersect.
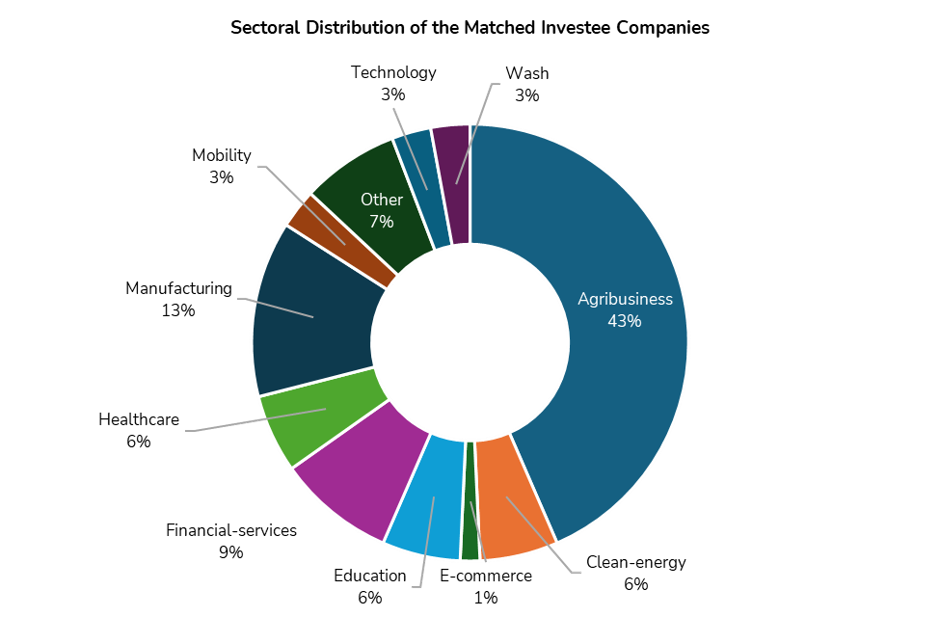
Agribusiness remains the largest segment of investee companies at 43 percent, followed by manufacturing, financial services, education, healthcare, and clean energy. These are sectors with strong potential for job creation and broad-based economic participation, particularly for underserved and rural populations.
To date, the Deal Flow Facility has supported deals worth over US$10.8 million across agriculture, financial services and light manufacturing through a mix of debt and equity investments. Financial services account for the largest share of capital raised, reflecting the strategic importance of inclusive finance institutions in expanding access for underserved populations.
Supporting investment into these sectors strengthens the wider financial inclusion agenda by ensuring capital reaches businesses that directly affect livelihoods, productivity, and resilience at the last mile.
Rather than treating financial inclusion only as access to credit for individuals, the DFF recognises that inclusive finance also depends on strong enterprises that can absorb capital, create markets, and expand opportunity.
Generating market insights for stronger capital markets
In 2025, the DFF also commissioned research to better understand Uganda’s private capital ecosystem and the barriers limiting investment flows.
The findings reinforced a key lesson: Uganda’s investment ecosystem requires solutions that are locally grounded rather than imported from more mature markets.
Investor readiness programmes must be tailored to local business realities and sector dynamics. At the same time, fund managers need a stronger understanding of Ugandan enterprises and more flexible investment strategies that reflect the realities of growth-stage businesses.
The research also highlighted the importance of stronger public-private coordination. Government has a catalytic role to play through more efficient legal processes, stronger support for blended finance models, and partnerships that crowd in private investment.
Local capital mobilisation remains another priority. While foreign capital continues to play an important role, greater mobilisation of domestic institutional capital, including pension funds and high-net-worth investors, will be critical for long-term sustainability.
Additional priorities include improving business development services, strengthening ecosystem talent across investment professions, and improving data sharing through more credible market information systems.
These are not isolated recommendations. Together, they point to the need for a stronger market architecture where investors, businesses, regulators, and service providers can operate with greater confidence and efficiency.
Looking ahead
The next phase of the Deal Flow Facility will focus on sustainability and institutionalisation.
Engagements with potential donors and other stakeholders such as the Ministry of Finance, Planning and Economic Development and the Capital Markets Authority, are helping shape pathways for the facility beyond current grant funding. An Information Memorandum and financial model were also developed to support future fundraising and long-term positioning.
The objective is to move beyond individual transactions and strengthen Uganda’s long-term investment ecosystem.
Financial inclusion is not only about access to finance at the household level. It also depends on whether businesses can access the right kind of capital to grow, employ, and serve others.
By unlocking patient capital for enterprises that matter, the Deal Flow Facility helps build a financial system that supports both inclusion and economic transformation.
Building trust, reducing friction, and expanding inclusion through digital public infrastructure
Building trust, reducing friction, and expanding inclusion through digital public infrastructure
A more inclusive digital economy depends on more than access to technology. It requires systems that are trusted, interoperable, and able to serve users across the entire financial ecosystem from large financial institutions to Tier IV providers and low-income consumers at the last mile.
FSD Uganda’s Digital Economy pillar focuses on reducing friction and strengthening trust through digital public infrastructure (DPI). DPI refers to the shared digital systems such as payments, digital identity, data Exchange, and fraud prevention that make financial services safer, faster, and more accessible.
Through this work, FSD Uganda supports stronger interoperability, better consumer protection, improved fraud prevention, and more efficient movement of data and payments across the financial ecosystem. The goal is to ensure that digital financial services are not only accessible, but also trusted, affordable, and inclusive for all Ugandans.
In 2025, this work focused on strengthening the foundations that enable the ecosystem to function better. This included supporting the review of Uganda’s National E-Payments Strategy, strengthening fraud prevention systems, improving fintech participation in the payments ecosystem, and expanding low-cost investment opportunities for ordinary Ugandans.
Strengthening the payments ecosystem
As digital payments continue to grow, the sector faces a new challenge: ensuring that growth translates into affordability, trust, and real usage.
FSD Uganda supported the Bank of Uganda in conducting the end-term review of the National E-Payments Strategy (2021–2026), which was designed to support Uganda’s transition toward a cash-lite economy.
The review showed strong progress on the supply side. Legal and regulatory frameworks improved, payment infrastructure expanded, and innovation accelerated. However, these gains did not automatically translate into stronger usage. Persistent reliance on cash remains driven by demand-side barriers such as high transaction costs, low transaction limits, limited digital literacy, and weak consumer trust.
The review also highlighted the absence of a national switch, which continues to contribute to market fragmentation, higher costs, and inefficient cash-in cash-out processes. At the same time, rapid growth in digital payments has increased exposure to cyber fraud, reinforcing the need for stronger consumer protection and faster redress mechanisms.
These findings reinforce an important lesson: infrastructure alone is not enough. Digital payments scale when users trust the system, understand its value, and can use it affordably.
Expanding inclusion beyond formal banking
For digital public infrastructure to drive inclusion, it must work beyond banks and large regulated institutions. It must also serve Tier III and Tier IV providers, fintechs, SACCOs, and the wider ecosystem where most underserved users interact with financial services.
In 2025, FSD Uganda supported The Financial Technology Service Providers Association of Uganda (FITSPA) to develop Third-Party Guidelines for Fintechs operating within the National Payment Systems framework.
Many fintechs continue to face overlapping licensing requirements, restrictive partnership models, and limited pathways to work legally and efficiently with regulated institutions. The proposed guidelines provide a clearer framework for licensed fintechs to partner with third-party providers while improving compliance and reducing barriers to innovation. The guidelines were finalised and submitted to the Bank of Uganda for ratification.
This work is important because inclusive digital finance depends on an ecosystem where smaller providers can participate safely and competitively not only where large institutions dominate.
Protecting trust in the digital financial system
As digital finance expands, trust becomes a public good. Fraud, weak data protection, and poor customer redress can quickly undermine adoption and confidence.
In 2025, FSD Uganda and the Uganda Bankers Association advanced Phase II of the Cyber Security Operations Centre (CSOC). While Phase I focused on establishing a fraud incident reporting portal, Phase II expanded this into a stronger shared defence system for the financial sector.
This work provided the foundation for the launch of the Financial Sector Anti-Fraud Consortium (FS-AFC), Uganda’s first cross-sector alliance against financial fraud.
Adoption of the fraud incident reporting portal expanded from 21 member banks to 59 Bank of Uganda supervised financial institutions, including banks and payment service providers, with active participation from regulators and enforcement agencies.
This demonstrates how targeted investments in shared infrastructure can create broader system resilience and improve confidence across the market.
Strengthening consumer protection and data privacy
Trust also depends on how well consumers are protected and how safely personal data is handled. FSD Uganda supported the Personal Data Protection Office to develop a professional curriculum on data protection and privacy, aligned to the Data Protection and Privacy Act (2019).
The project addressed a growing skills gap as institutions sought to comply with new legal requirements but lacked trained personnel. It concluded with a Training of Trainers programme that certified 40 professionals who can continue to support data privacy capacity building across the sector.
Alongside this, FSD Uganda continued engagement with regulators on stronger customer redress mechanisms, consumer protection standards, and financial literacy.
As digital finance grows, consumer trust will depend not only on access, but on confidence that systems are fair, secure, and responsive when problems arise.
Expanding access to investment opportunities
Financial inclusion must go beyond access to payments and savings. It must also help people build resilience, plan for the future, and grow wealth over time.
FinScope Uganda 2023 shows that more than seven in ten Ugandans have no concrete long-term financial plans, only 11 percent are satisfied with their financial situation, and 60 percent are not confident about financial security in old age.
These findings point to an important gap: many low-income Ugandans remain excluded from safe, formal investment opportunities.
In 2025, FSD Uganda supported the Ministry of Finance and Bank of Uganda in launching Okusevinga, a mobile government securities platform that allows retail investors to buy and sell government securities using mobile phones.
With a minimum investment of UGX 10,000, the platform significantly lowers the barrier to entry for government investments and opens access to a market that has traditionally been limited to higher-income investors.
Okusevinga demonstrates how digital public infrastructure can support not only financial inclusion, but also wealth creation and broader participation in capital markets.
Looking ahead
The digital economy is no longer only about digitising transactions. It is about building systems that are trusted, connected, and inclusive.
In 2026, FSD Uganda will continue to support stronger interoperability, broader inclusion of Tier III and Tier IV institutions, improved consumer protection, and shared infrastructure that reduces fraud and strengthens resilience across the financial sector.
The focus will remain on ensuring that digital public infrastructure works not only for large institutions, but also for smaller providers and low-income users at the last mile.
The objective is clear: to make digital financial services safer, more affordable, and more accessible for all Ugandans.