Blended Finance Catalysing Financial Inclusion in Uganda

Blended Finance Catalysing Financial Inclusion in Uganda

    Download Publication

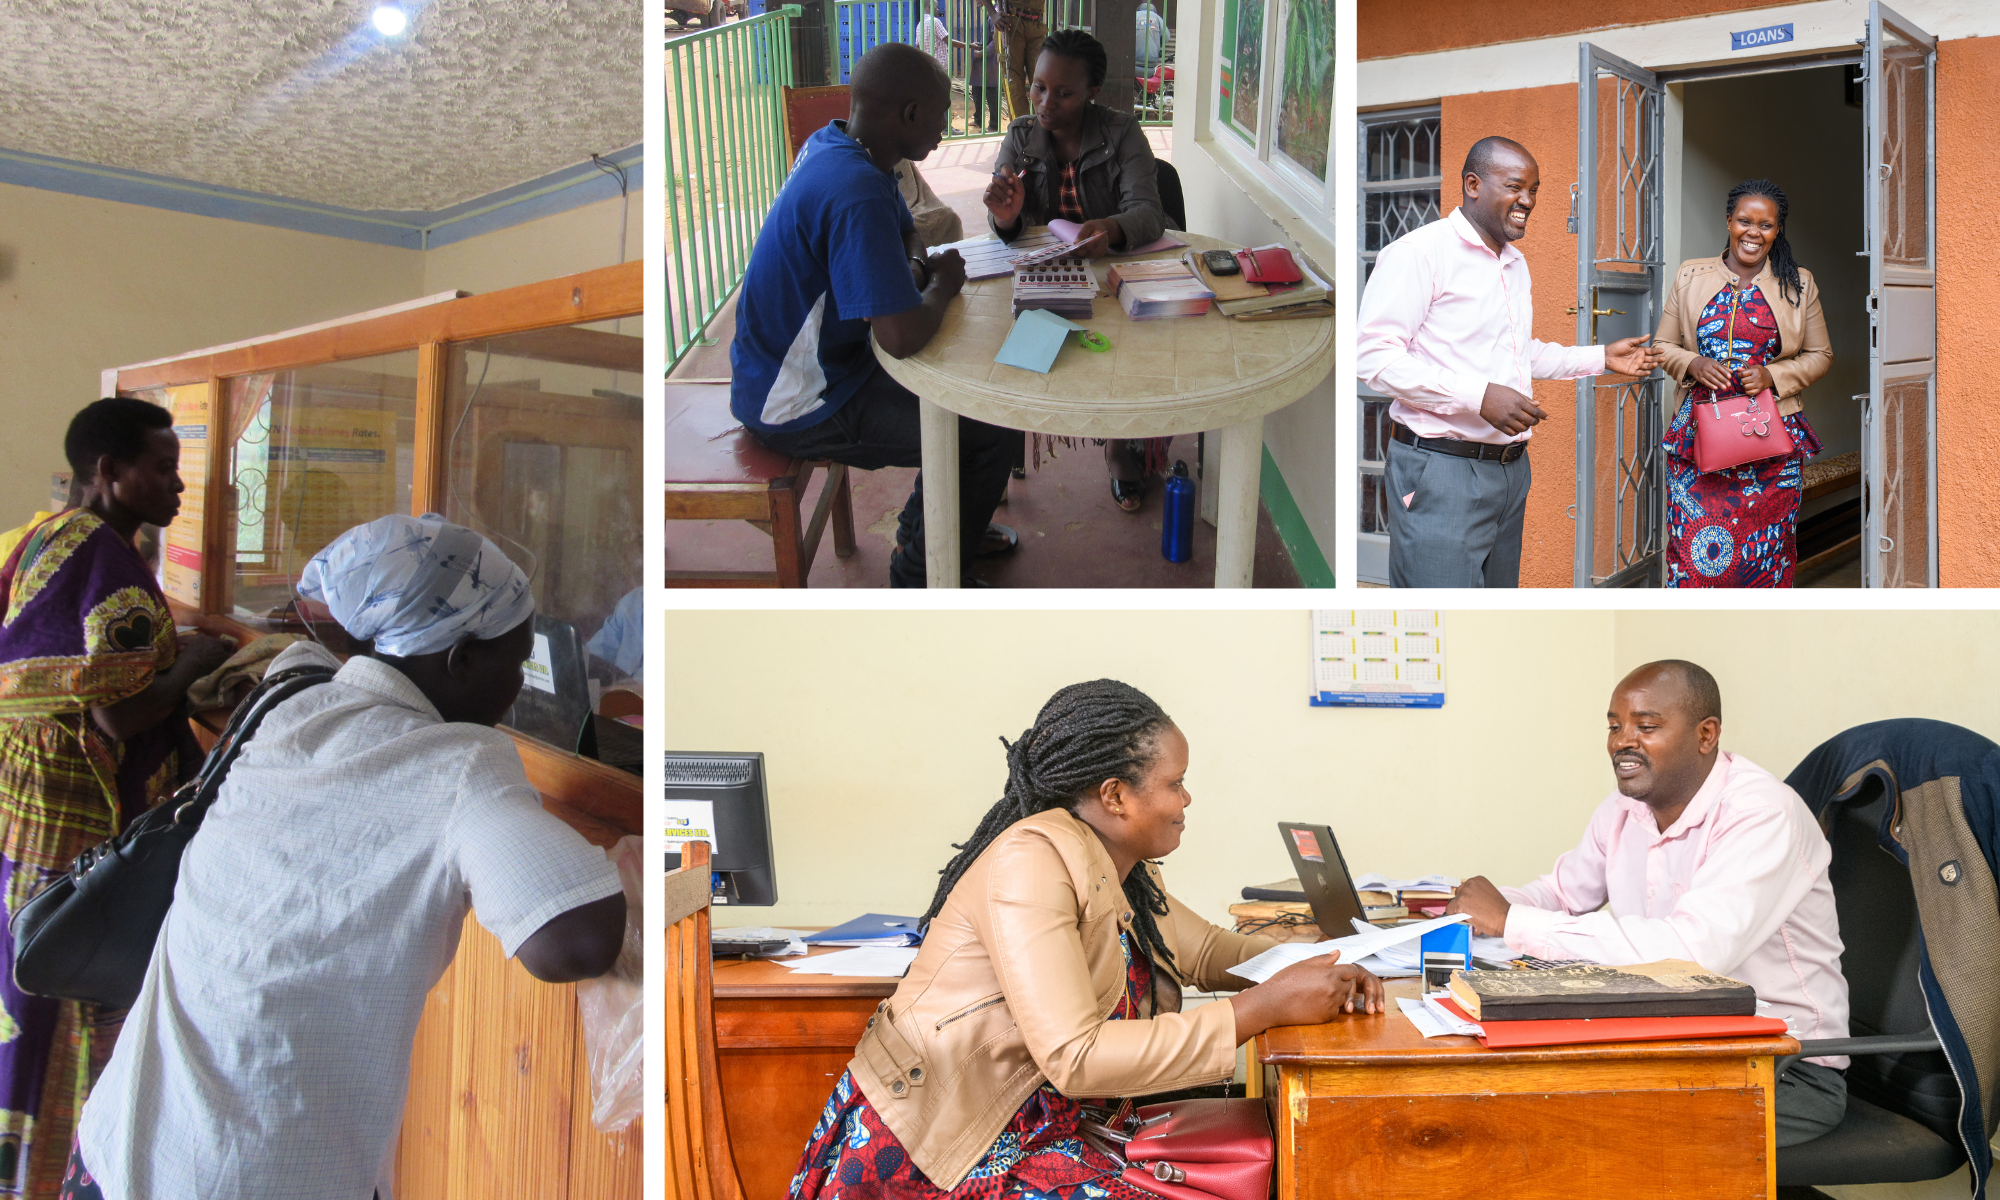
    The study of the three blended finance funds, the Micro and Small Enterprises (MSE) Recovery Fund, the Agricultural Credit Facility (ACF) and the Small Business Recovery Fund (SBRF) shows that blended finance can indeed have a catalytic impact on access to formal financial services. However, the cost of finance remains high despite increased access for the case of the MSE Recovery Fund. For the ACF and SBRF, where the interest rates are fixed, these cannot be sustained without the continual interest free government contribution.

    Therefore, for sustainable impact to be achieved by such initiatives, an integrated approach that combines technical support and blended finance to address both the supply-side and demand-side structural and behavioural bottlenecks is critical

    Share:

    Data sets – FinScope Uganda 2023 Survey Dataset

    Data sets – FinScope Uganda 2023 Survey Dataset

      Download Dataset

      Share:

      Enhancing financial inclusion beyond alternative credit scoring: Empowering underserved markets

      Enhancing financial inclusion beyond alternative credit scoring: Empowering underserved markets

      By Joseph Lutwama

      Setting the scene

      Alternative Credit Scoring (ACS) or use of non-traditional data such as airtime purchases and mobile money transactions to assess bankability, has been touted as one of the solutions that could open the formal credit markets to the underserved market segments.

      Already widely used by emerging digital lenders-both fintechs and digital savvy incumbents, ACS has indeed extended the financial inclusion frontier for underserved market segments.

      Such alternative data shades light on the risk profiles and untapped business opportunities of market segments that until now were considered untouchable and unreachable. Despite making in-roads into previously untapped credit markets through ACS, the cost of credit remains high and the amounts of credit available to customers in these new markets remains limited and for much shorter loan tenures. Therefore, if the credit markets are going to provide meaningful and lasting impact to these new market segments, we need to think beyond alternative credit scoring mechanisms.

      The credit market environment

      Despite gains made to date with over 60 percent1 of Ugandan adults using mobile money financial services, active usage of formal financial services remains low. Less than 10 percent2 of Ugandan adults access their credit from regulated commercial banks. Several reasons explain this state of affairs the major one being a lack of collateral.

      Collateral is a prerequisite for anyone seeking for a loan from a regulated financial institution. In most cases this is physical collateral in the form of land or real estate property. While 70 percent3 of Ugandan adults own land, less than 10 percent4 have formally registered land titles. This renders their properties and land ineligible to act as collateral for any form of financial transaction.

      A case has been advanced that there is more to credit risk than the availability of physical collateral. This line of argument presupposes that one can be credit worthy even without physical collateral, if they are running a profitable business or they have verified, consistent and regular income. This is information that previously was not accessible due to the high levels of informality among most Ugandan businesses. With the current prevalent use of mobile money, it is possible to capture and track a vast wealth of customers’ digital activity that financial institutions can leverage to offer financial services to previously underserved market segments. This has resulted in the increased adoption of alternative credit scoring mechanisms away from credit risk frameworks that rely heavily on physical collateral. A new product category of digital loans targeting a previously underserved market segments has emerged offered by both emerging digital credit providers and digital savvy incumbents.

      These loans are usually very short term not exceeding 30 days and in rare cases not exceeding 6-12 months. They are tied to the personal and business financial transactions of the customer and they are designed not to exceed the volume and velocity of the money in the customer’s digital wallet. The maximum amounts one can borrow will be based on the money balances in one’s digital wallet and how many times they move money through their digital wallet. The higher the velocity and balances in one’s digital wallet the greater the chances of accessing a digital credit facility. However, this usually comes at a very high cost.

      Taking the example of the MSE Recovery Fund, a liquidity facility that advances credit to micro and small businesses most of which do not have physical collateral. The digital lenders accessing the MSE Recovery Fund and using alternative credit scoring mechanisms have the highest costs of credit. One of the lenders charges an annualised interest rate exceeding 140 percent per annum. While this credit is issued in average tenures of not more than a week which has made it affordable, beyond a month the costs become untenable. Likewise on average the loan amounts do not exceed Ushs 500,000 on average. This keeps these customers perpetually small with limited or no capacity to grow and scale into much bigger businesses.

      Beyond alternative credit scoring mechanisms

      Therefore, much as alternative credit scoring increases the chances of accessing credit for previously underserved market segments, for most of the customers in these market segments it only magnifies their already high-risk profile. The result is limited credit limits at very high interest rates and in some adverse cases further exclusion. Therefore, if alternative credit scoring is going to have meaningful and lasting impact on the underserved market segments, it needs to be combined with business development support and financial capability training for the target customers. This will greatly reduce their risk profile and increase their chances of accessing much higher credit limits for much longer tenures than is currently the case.

      Share:

      Leveraging Technology to Increase Access to Rural Agricultural Credit Finance: The Case of Emata

      Leveraging Technology to Increase Access to Rural Agricultural Credit Finance: The Case of Emata

      By Douglas Karugonjo, Joseph Sanjula Lutwama and Maren Hald Bjørgum

      The State of Rural Agricultural Credit Finance

      Agriculture in Uganda especially in the rural areas has always faced the challenge of limited access to credit finance. As of the end of March 2023, the agricultural sector accounted for 11 percent1 of the commercial bank credit to the private sector despite accounting for the highest proportion of Uganda’s labour force at 35.9 percent2. Most of this limited funding is allocated to commercial large-scale agricultural production, processing, and trade with the least going towards small-holder farm production which dominates the rural areas.

      Given its predominantly informal nature with heavy reliance on rudimentary agronomical practices, formal financial institutions are hesitant to advance credit to small-holder farm production. First and foremost, these farmers are in far to reach remote areas making it costly to serve this market segment. Additionally, the potential return on investment from this market segment is very low considering the informal nature of their farm production units. Their production levels are highly unpredictable and susceptible to adverse weather patterns and fluctuating market prices. Combined, these factors make this market segment risky and barely profitable.

      The Promise of Technology

      Despite all the disadvantages associated with small-holder farming, technology presents a unique opportunity that could turn this market segment into a viable and profitable business opportunity for formal financial service providers.

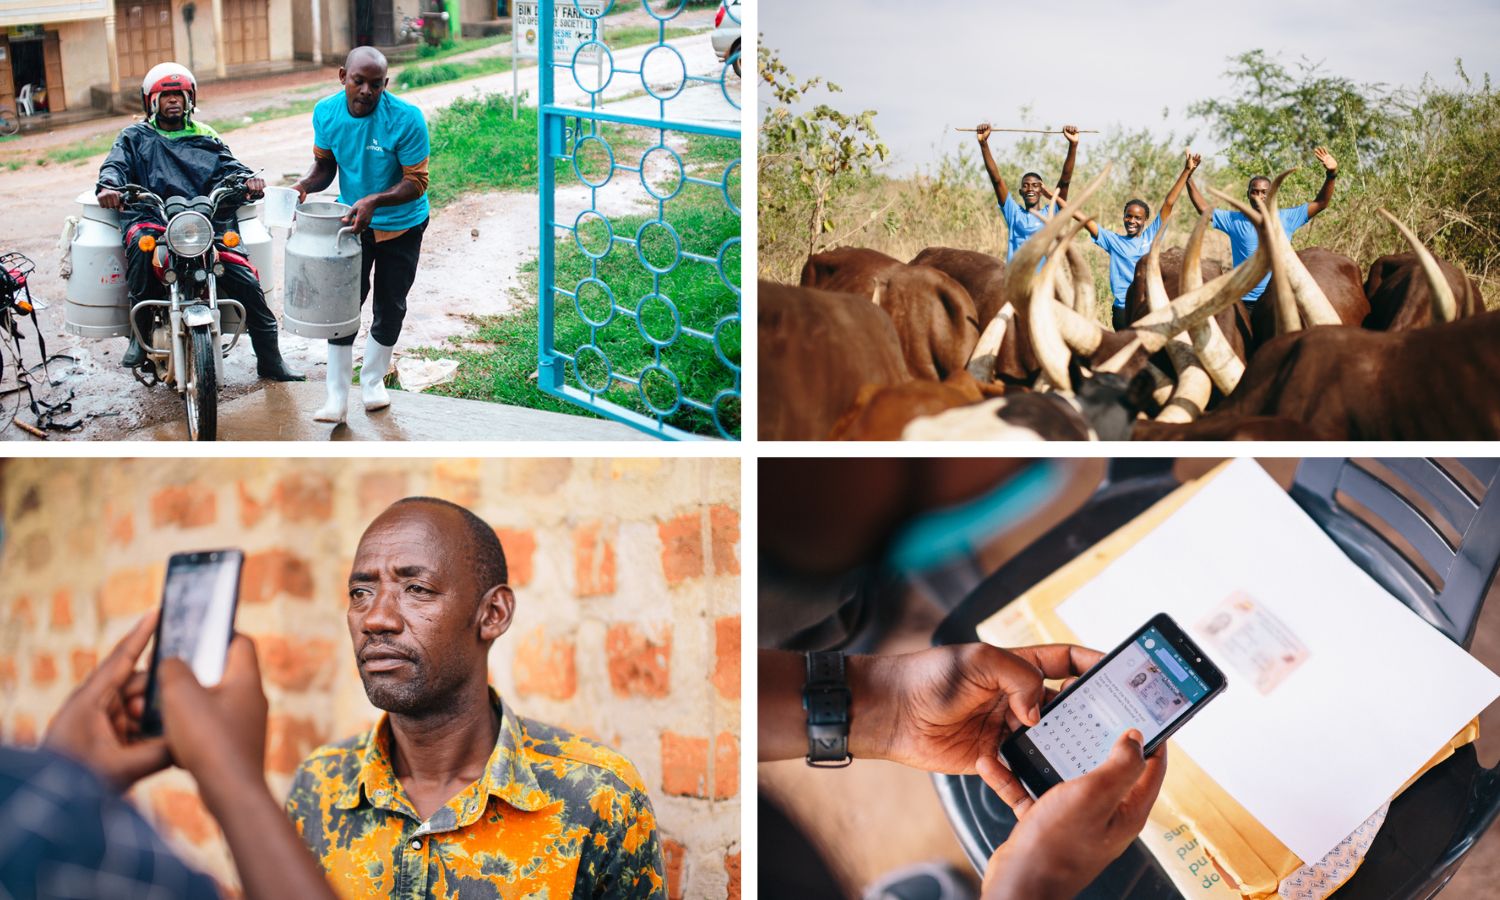
      In 2019, the Financial Sector Deepening (FSD) Uganda partnered with Laboremous Uganda Limited to pilot its technology platform Emata in delivering affordable and easily accessible credit to dairy small-holder farmers in Central and Western Uganda. The partnership was focused on digitising farmer records and creating credit scores that could help farmers access credit. FSD Uganda also provided technical assistance towards a human-centred approach to product design for the loan origination and repayment process on the Emata platform. After a successful pilot, Emata was officially registered as a company in March 2020. It received its lending license in December 2020 and started lending in February 2021.

      Emata meets the need for agricultural financing by providing affordable digital loans to farmers that are three to six times more affordable than informal loans that smallholder farmers use today. Emata achieves this by digitising the entire process and servicing farmers via partnerships. The Emata model effectively solves the challenges that formal financial institutions face when financing farmers regarding manual processes, last mile distribution, and the need for collateral.

      Whereas banks largely rely on manual processes, Emata automated the entire process from data collection, credit processing, to loan disbursement. This high level of digitisation brings many advantages. First and foremost, it reduces the costs of processing a loan. This enables Emata to provide small loans that are suitable for smallholder farmers. The high level of digitisation also makes Emata’s lending decision instant. This means farmers no longer have to wait for months before they know if they will have the funds, they require to make critical and often time-bound investments.

      The Emata model effectively addresses the issue of last mile distribution. Emata loans are requested through WhatsApp, by using an automated chatbot. WhatsApp is widely popular in Africa, very data efficient, and eliminates the need to install a separate app. Farmers without WhatsApp can use the smartphone at their dairy cooperative. This allows Emata to reach even the most remote farmers without a smartphone.

      Emata reduces the need for collateral by building its credit decisions on data science. Emata uses the patterns of the farmers’ production data, weather data, and satellite data to determine how much a farmer produces, if a farmer is reliable, and ultimately lendable. This data science driven approach allows for better decision-making that reduces the risk and thus the need for collateral. This allows Emata to service all farmers, regardless of whether they are men, women, or youth – and not just the large-scale professional farmers with collateral.

      How the Emata platform works

      Rather than going to each farmer individually, which would be costly, Emata partners with cooperatives and comparable organisations. The Emata process can be broken down into three steps. First, Emata provides software to partners to digitise their operations via a user-friendly Management Information System (the Emata “MIS”). The Emata MIS unravels administrative clutter, increases transparency, and allows cooperatives to make data-driven decisions.

      Second, Emata covers the data collected via the MIS and 3rd party weather and satellite data into credit limits tailored to each farmer. Emata achieves this by using algorithms that forecast production, income, and cash available to repay the Emata loan.

      Lastly, Emata provides digital loans that farmers request through a WhatsApp chatbot. Loans are disbursed via mobile money or to input suppliers.

      The Impact in numbers 

      Between August 2019 and July 2022, a total of 56 dairy cooperatives signed up on the platform with 57 percent active. Over 9,000 farmers were active on the platform with digitised agricultural production records. 80 percent of these were in the dairy sector, with the remainder divided between the oil seeds, maize, and coffee sectors.

      During that period, a total of 1,464 loans were advanced to farmers with the dairy sector accounting for the bulk (85 percent) of the credit disbursed. The Emata  platform also provided competitive interest rates that are multiples lower than the market range of 10 percent to 20 percent per month.

      The Emata platform also registered good performance about the credit portfolio health of the farmers especially the dairy farmers, with a default rate below 1% and PAR-30 below 5%. This is a clear testament to the value of technology in reducing the risk profile of the small-holder farmer.

      From Small-Holder Financing to Unlocking Ecosystem Financing Opportunities

      Overall, the Emata platform has transformed the dairy ecosystem beyond increasing access to agricultural finance for the small-holder dairy farmers to opening potential financing opportunities for other dairy ecosystem actors. The dairy cooperatives benefit from the free-of-charge administrative platform of Emata which resolves the burden of manual record keeping and reduces the time spent preparing semi-monthly payments to farmers from four days to a few clicks. Entering records on the Emata platform is cost and timesaving for the cooperatives thereby boosting operational efficiency and profitability. Moreover, membership and milk deliveries are boosted as access to affordable credit becomes a key reason for farmers to join a cooperative.

      A Catalyst for Economic Empowerment

      Given that the dairy sector is one of the fastest growing export sectors in Uganda yielding 2.08 billion litres of milk, the highest in East Africa, Emata presents an immense economic empowerment opportunity for the small-holder dairy farmers. Given the easy access to credit financing, smallholder farmers can now take advantage of these immense economic opportunities in Uganda’s dairy sector.

      Share:

      Empowering Micro, Small, and Medium Enterprises: The Influence of Microfinance Group Lending
      Empowering Micro, Small, and Medium Enterprises: The Influence of Microfinance Group Lending

      By the MicroSave Consulting and FSD Uganda teams

      Across the globe, the lack of collateral is a primary barrier that economically excludes individuals notably young people especially women from accessing formal banking services. To get around this obstacle, the underserved population has resorted to establishing informal community-based financial systems to fulfill their financial requirements. These alternative arrangements, such as Village Savings and Loans Associations, Rotating Savings and Credit Associations, and Table Banking, have emerged as a means for the marginalised to access the financial resources they lack from traditional banking institutions. To extend financial services to the underbanked and unbanked, formal financial institutions have emulated and adopted some of the positive practices in the informal financial systems.

      Informal or formal, financial institutions that offer loans use one of two approaches, individual or group lending. This is the same with the Tier III and IV financial institutions that are on-lending under the Mastercard Foundation Micro and Small Enterprises (MSE) Recovery Fund, a five-year program implemented in partnership with the Financial Sector Deepening Uganda. This initiative was launched in February 2022 and is under the Young Africa Works strategy, which seeks to facilitate direct access to finance 50,000 MSEs (at least 40% women, 30% youth). Designed during the aftermath of the COVID-19 pandemic, this revolving fund provides concessional capital to participating financial institutions for onward lending to micro, small, and medium enterprises negatively impacted at a reduced borrowing rate. The participating financial institutions follow their in-house credit processes to assess the enterprises given their needs.

      Group lending vs individual lending

      The Fund is working with both Tier 3 and Tier 4 financial institutions. Based on the data so far, one Tier 3 Microfinance institution has effectively employed the group lending methodology for a broader client outreach. Since the Fund’s commencement (just under two years), over 26,000 MSEs have successfully accessed credit, and 60% of this has been disbursed by the Microfinance, a testament to its distinctive strategy. The Microfinance has disbursed UGX 7 billion to 16,166 majority of them youth and women-led enterprises within 12 months. Conversely, two SACCOs that employ an individual lending approach, have managed to extend credit to 842 and 503 enterprises and disbursed UShs 3.4 billion and UShs 2.25 billion respectively within 12 months.

      For both approaches, the critical difference is in the collateral criteria. With group lending, all that’s needed is a group guarantee, unlike individual lending products that demand traditional collateral. The Microfinance’s group methodology

      explores unique features that have positively impacted young people, especially women, and offers lessons for other financial institutions: Here is what makes this institution’s group lending approach work.

      How the Mircofinance’s group lending approach works

      Central to the approach is that the institution has dealt with the access to finance obstacle created by the need for traditional collateral. To do this, the institution employs the segmented and combined group strategy, coupled with the delegation of credit approval authority to group members.

      To implement this, the Microfinance employs a two-fold group methodology: branch-based and community-based groups. The former gathers at the bank, while the latter convenes locally, delivering tailored flexibility to diverse client needs.

      The institution looks out for people organised in groups and creates sub-groups of six to seven members to whom loans are exclusively accessible. These sub-groups operate like well-coordinated “cabinets,” complete with designated leaders. This structure not only encourages governance but also strengthens bonds among members. The institution’s loan officers play a modest role in the lending process. Group members collectively greenlight loans without the intervention of the bank. This empowers the groups, enabling them to take charge of credit underwriting, member selection, and loan recovery. This proactive approach ensures that disbursed amounts grow, and the quality of loans improves over time.

      Once the groups have been formed, members of branch-based groups can access loans up to UShs 5 million per member without the need for collateral. On the other hand, community-based groups can borrow up to UShs 3 million per member, securing approvals at the group level—an embodiment of the Microfinace’s dedication to client empowerment. For more substantial loan amounts, up to UShs 30 million, collateral is a requisite to manage potential risks. This balanced approach ensures that prudent risk mitigation measures are also upheld while empowering clients

      A client’s story

      Emily a 28-year-old tailor in Bukoto whose business was adversely affected by the Covid-19 pandemic is one of the Microfinance’s clients served under the group ledning model. Her faulty manual sewing machine didn’t help matters as it affected her output’s quality, efficiency, and income so much that she could hardly meet her daily basic needs. “Things changed when through my savings group which banks with the Microfinance, I received a loan of UGX 800,000 and bought an electric sewing machine,” she says.

      The tailor is now efficient, and her turnaround time has been reduced from three hours to one hour for some jobs. “This has helped me regain my client’s confidence and also get new clients. I now make at least UGX 15,000 daily and I can meet all my basic needs. This wasn’t the case before when I made no money on many days and had to skip some meals and move in with a relative because I couldn’t afford rent. Because of the increased volume of work, Emily is planning to employ one other person to support her.

      As a result, this dynamic formula has enabled the bank to extend credit to a broader spectrum of customers, especially women and youth who lack conventional collateral. Given that women are more likely to belong to groups, the group lending approach is one that financial institutions from Tier 1 to IV should learn from and integrate in order to reach young people, especially women

      Share:

      What does it take to make digital credit gender inclusive?

      What does it take to make digital credit gender inclusive?

        Download Report

        Digital lending is expanding rapidly across markets with significant mobile money or mobile banking penetration. And as with all financial services, access and utilization patterns differ by gender. Some digital lending may have the potential to overcome gender biases. For example, borrowers can request a loan from anywhere, avoiding some transaction costs that are particularly burdensome for women. It can standardize processes to avoid the human biases of loan officers. Lenders can work around gender biases stemming from the use of titled land as collateral by assessing creditworthiness on alternative data sources such as cash flows.

        But digital lending can still suffer from inequities. Women may have less access to smart phones, run smaller businesses deemed ‘unworthy’ by some lender, or lack certain forms of KYC required for applications. They may be more likely to struggle navigating a smartphone app on their own. And if the product itself wasn’t designed with women in mind, it may be a poor fit for their borrowing needs.

        How can digital lenders be conscious of the range of gender issues that might be at work and adapt their practices to be attractive and useful for women? FSD Uganda and the FSD Network Gender Collaborative Programme explored these issues through a partnership with a digital lender in Uganda from 2021-2023. FSD Uganda was simultaneously working with this lender to expand the pool of capital available to women borrowers in the aftermath of Covid and the Ebola outbreak by providing the lender a US$100,000 returnable grant specifically earmarked for on-lending to women’s businesses. We supplemented this with a targeted piece of research that involved reviewing existing gender data and interviewing male and female customers to identify where there might be opportunities for this lender to be more gender inclusive.

        The results point to both specific things this firm is doing right and where they might improve, while also providing a framework for how other firms might review their own data and practices in an effort to be more gender intentional.

        Share:

        Supporting refugees to find freedom by expanding access to finance

        Supporting refugees to find freedom by expanding access to finance

        By FSD Africa and FSD Uganda teams

        “Independence”, “having the power or right”, and “liberty”, are some of the phrases that describe freedom. This year’s World Refugee Day theme is ‘finding freedom’ and access to financial services is a key component to achieving that once refugees resettle so that they become self-reliant and economically independent.

        Though important, little has been known about the financial strategies employed by refugees over time to build their livelihoods and manage their finances.

        To learn more, the Financial Sector Deepening (FSD) Uganda and FSD Africa commissioned the Financial Inclusion for Refugees (FI4R) project. The project aimed at deepening and broadening access to and usage of formal financial services among refugee and host communities in Uganda, with a focus on the West Nile and South-West regions. The project also had a learning and research component to assess refugees’ incomes and expenses to inform the development of financial products and services offered to them in Uganda.

        Consequently, the project supported three financial institutions; Rural Finance Initiative (RUFI), VisionFund Uganda, and Equity Bank Uganda Limited to rectify this grim situation by enabling them to offer a variety of savings and credit products as well as financial literacy programmes to refugee groups in the target areas.

        Florence is one of many refugees who benefited from the Financial Inclusion for Refugees project by getting a RUFI loan through her savings group. The single mother of two who lives in the Palorinya refugee settlement in Moyo district arrived in the settlement five years ago from South Sudan. She is a tailor belonging to three saving groups where she saves Ushs 4,000 (1.04USD) and Ushs 20,000 (5.2USD) weekly in each group.

        She used the loan as capital for her business and continued to save money together with her group so that she can later purchase stock.

        Over a period of 12 months, Florence has increased her contributions to the savings group as she has realised saving diligently is essential to growing her business.

        Through its implementation, the project addressed some of the key barriers to increasing access to financial services for refugees including, low-risk appetite among the financial service providers highlighted by the limited appreciation of refugees as a potential market and underdeveloped ecosystems where there is high reliance on saving groups and limited adoption of formal financial services.

        In addition to evaluating the impact of financial services on refugee livelihoods in Uganda, the learning and research component also provided insights for financial institutions on how to improve access to financial services in the refugee settlements.

        The project endline study reports that Ushs 7.6 bn was disbursed in loans by the three financial institutions to savings groups. Additionally, over Ushs 12 bn was deposited in savings accounts with three financial institutions.

        Florence’s experience and the endline report numbers demonstrate that refugees are a viable market segment. For that to be fully exploited, respondents’ reasons for hesitation to use formal financial services must be tackled.

        Interested commercial banks and micro-financial institutions should therefore improve access by deploying more agents in the different villages of the settlement. This is in place of having a few agents in the major trading centers which are far away from the settlements.

        Additionally, information regarding details of products and services offered including interest rates, fees, and prerequisites should be availed and simplified even when services are offered digitally.

        Further, the high transactional costs of using mobile money should be revised as these were sighted as a reason for limited or avoidance of usage.

        When these adjustments are made, financial service providers will register transactions worth more than the recorded Ushs 7.6 bn and Ushs 12 bn in loans and deposits/savings respectively in the two years of the Financial Inclusion for Refugees project’s implementation. This will make financial inclusion for refugees and host communities a win-win for financial service providers whose decisions are profit based as well as the target market segment.

        Share:

        FI4R Diaries Round IV Insights: Gender

        FI4R Diaries Round IV Insights: Gender

          Download Case Study

          This is the final(part four) of an ongoing series of insights from a financial diaries study undertaken with refugees in Uganda, focused on their ability to cope with risks. The respondents are drawn from customers served by three financial service providers: Equity Bank Uganda, VisionFund Uganda, and the Rural Finance Initiative.

          Share:

          FI4R Diaries Round III Insights: Digitization of Saving Groups

          FI4R Diaries Round III Insights: Digitization of Saving Groups

            Download Case Study

            This is part three of an ongoing series of insights from a financial diaries study undertaken with refugees in Uganda, focused on their ability to cope with risks. The respondents are drawn from customers served by three financial service providers: Equity Bank Uganda, VisionFund Uganda, and the Rural Finance Initiative.

            Share:

            Covid – 19 Market Diagnostics and Options for Long-Term Recovery (Supply – Side Report)

            Covid – 19 Market Diagnostics and Options for Long-Term Recovery (Supply – Side Report)

              Download Report

              The overall objective of the study was to develop practical solutions for preserving and building relevant elements of the financial system to support the survival, recovery, and growth of micro and small enterprises (MSEs) in Uganda. The core of the market analysis was to understand how the supply of finance to the MSE sector in Uganda had been affected by the COVID-19 crisis and what options were available to build on ready measures to mitigate the impact. This analysis identified both threats and opportunities for inclusive finance service providers (IFSPs) to meet the financing needs of MSEs.

              With the support of the Association of Microfinance Institutions of Uganda (AMFIU) and with some direct provision of information by IFSPs, the study team had detailed operational and financial information on 30 SACCOs and 11 MFIs. Due to confidentiality/nondisclosure policies, AMFIU provided anonymous data, stating only the region in which the entity operates and its institutional form.

              Share:

              Covid – 19 Market Diagnostics and Options for Long-Term Recovery (Demand- Side Report)

              Covid – 19 Market Diagnostics and Options for Long-Term Recovery (Demand- Side Report)

                Download Report

                The COVID-19 pandemic has had significant impact on the Ugandan economy especially hitting the micro- and small enterprises (MSEs) in the informal sector. MSEs have been facing unprecedented income losses and uncertainties about their future because of business disruptions due to the outbreak of COVID-19.

                FSD Uganda commissioned a demand side market diagnostic study to assess the impact of COVID-19 on micro and small enterprises in Uganda. The overall objective was to develop practical solutions to preserve and build relevant elements of the financial system to support the survival, recovery and growth of micro and small enterprises in Uganda.

                From the research, only 3% MSEs reported to be completely recovered. 71% of the surveyed MSEs are yet to return to normal pre-COVID-19 operations timing. Several factors such as reduced hours of operation, disruptions in movement, and general low customer turnout have impacted the businesses severely.
                MSE owners hope to bounce back, however, some issues continue to plague the recovery of enterprises. These include, on an average 50% of reduction in household income due to low revenue from the business, job losses in the family, or depletion of other income sources hit by the pandemic.

                Women-led enterprises have suffered a greater average loss in income (50%) compared to men-owned MSEs (33%) from the pre-pandemic level of income. Also, while MSEs in urban areas have been able to attain 57% of the pre-pandemic income level, MSEs in rural areas have recovered up to 50% of the pre-pandemic income level.

                As per the estimates of the World Bank, the COVID-19 crisis has pushed around 2.6 million Ugandans into poverty. With longest closure of schools in Uganda, not only the education sector but many other businesses providing services in the ecosystem suffer a great deal in their bid to recovery to pre-pandemic level.

                Share:

                Rebuilding livelihoods in displacement Endline Report – March 2022

                Rebuilding livelihoods in displacement Endline Report – March 2022

                  Download Case Study

                  Little has been known about the financial strategies employed by refugees over time to build their livelihoods and manage their finances. This report provides an in-depth analysis of a baseline survey undertaken in January 2020 and an endline in November 2021. The sample included refugees and their host communities in the settlements of Nakivale, Bidi Bidi, Palorinya and in the capital Kampala. An endline study was conducted to understand the evolved financial behavior of refugees, get feedback on financial products offered by the implementing partners and assess how new financial products were used by the refugees. The COVID-19 pandemic occurred during the study period and offered the opportunity to track how households coped with the situation.

                  The Financial Inclusion for Refugees (FI4R) project was launched in 2019 by FSD Uganda and FSD Africa to support financial service providers (FSPs) to offer financial services to refugees and host communities. The project is supporting three financial service providers (FSPs) Equity Bank Uganda Limited (EBUL), Vision Fund Uganda (VFU) and Rural Finance Initiative (RUFI) to offer financial services to refugees and host communities.

                  Share:

                  Financial Inclusion for Refugees Case Study in Uganda

                  Financial Inclusion for Refugees Case Study in Uganda

                    Download Case Study

                    To credit Henry J. Leir Institute – The Fletcher School of Law and Diplomacy

                    During a year that most of the world has spent locked indoors, we should remember that 1% of the world’s population has been forced to flee their homes due to conflict or persecution. This is roughly 79.5 million people. 26 million are refugees, and almost half are under the age of eighteen. Nearly three-quarters of displaced persons are hosted by neighboring countries, which often are in need of help themselves.

                    Share:

                    The Overall Impact of COVID on The Economy; An Agile Scenario Analysis

                    The Overall Impact of COVID on The Economy; An Agile Scenario Analysis

                      Download Report

                      This agile scenario analysis conducted in partnership with the Ministry of Finance, Planning and Economic Development and The Bank of Uganda explored the potential short and mid-term economic effects the pandemic would have on the key labour segments. Using additional insights from ongoing economic recovery efforts, the team also identified the potential role various sectors could play in strengthening the inclusiveness of the country’s recovery efforts.

                      0 Comments
                      Share:

                      The Impact of COVID on Agriculture in Uganda

                      The Impact of COVID on Agriculture in Uganda

                        Download Report

                        Earlier studies conducted by FSD Uganda indicate that specific segments of the population – including people who directly or indirectly rely on farming – will be severely affected by the impact of COVID-19 pandemic. We conducted a rapid diagnostic to understand how agricultural finance in Uganda has been affected, to inform financial market-led recovery efforts. Findings from the study have been used to strengthen FSD Uganda’s new five-year agricultural portfolio.

                        0 Comments
                        Share:

                        Assessing the Economic Resilience of Ugandan Households During COVID

                        Assessing the Economic Resilience of Ugandan Households During COVID

                          Download Report

                          This phone-based survey conducted between April 2020 to September 2020 over five waves provides a detailed analysis on the resilience of the sample surveyed. It demonstrated:

                          0 Comments
                          Share:

                          Our Donors & Partners

                          European Union Logo
                          Report a concern anonymously

                          FRAUD AND ETHICS HOTLINE

                          Subscribe to our PUBLICATIONS

                          OUR CONTACTS

                          ADDRESS:

                          Plot 20B, Kawalya Kaggwa Close, Kololo
                          P.O. Box 608, Kampala – Uganda

                          TEL: +256 393 231260/2

                          © Copyright FSD Uganda 2015 – 2024. All Rights Reserved.